Author

admin

Browsing

Payroll has a way of turning into a weekly source of tension. You hire people because your business is growing, then the back office gets heavier, deadlines get tighter, and one missed tax deposit or overtime mistake can follow you for months. You are not imagining the pressure. Payroll touches cash flow, compliance, employee trust, and your own peace of mind, all at once. Many business owners turn to accounting and tax services Fort Worth to reduce errors, stay compliant, and regain control.

That is why many owners turn to a Certified Public Accountant instead of trying to keep every payroll task in house. The right firm does more than run paychecks. It organizes records, applies tax rules, tracks wage laws, and builds a process that keeps small mistakes from becoming expensive ones. How Certified Public Accounting Firms Streamline Payroll Services comes down to one thing. They replace a fragile, manual routine with a reliable system.

Certified public accounting firms reduce payroll errors before they spread

Most payroll problems start small. A worker changes withholding and the form never gets entered. A bonus is taxed the wrong way. Someone works through lunch, and the time record does not reflect it. In the moment, each issue feels fixable. Then quarter end arrives, payroll taxes do not match, and your team starts asking why their net pay changed.

Certified public accounting firms are built for this kind of detail. They standardize how employee data is collected, how hours are approved, how deductions are applied, and how payments are recorded in the general ledger. That structure matters because payroll is not only math. It is timing, documentation, and compliance. The IRS expects employers to follow federal withholding and deposit rules, and the agency lays out those obligations in its Employer’s Tax Guide. Missing one part of that chain can trigger penalties that feel deeply unfair when you were simply trying to keep up.

A CPA firm also sees the patterns that busy owners often miss. If payroll keeps changing at the last minute, if contractor classifications look shaky, if overtime is rising without controls, those are warning signs. You may only feel that payroll is getting harder. A professional payroll accounting service can point to the exact reason.

Payroll compliance gets harder as your team grows

The first employee changes everything. The fifth or tenth employee usually exposes the cracks. You are no longer paying one or two people from a spreadsheet. You are managing new hire reporting, time tracking, withholding forms, benefit deductions, wage garnishments, paid leave questions, and state or federal labor rules. If tipped employees are involved, wage calculations become even more sensitive, and the Department of Labor rules on wages and tips can affect how you pay and document compensation.

This is where many businesses lose hours they cannot spare. You might spend Friday fixing timecards, Monday answering payroll questions, and the rest of the week worrying whether you categorized everyone correctly. The Small Business Administration also outlines core employer responsibilities when you hire and manage employees, and payroll sits at the center of those duties.

CPA payroll services help by connecting these moving parts. Instead of payroll living in isolation, it gets tied to onboarding, bookkeeping, tax filings, and year end reporting. That reduces rework and gives you cleaner numbers for budgeting and planning. A payroll run should not feel like a fire drill.

DIY payroll and professional payroll support create very different outcomes

Area DIY Payroll Certified Public Accounting Firm
Data entry Often manual, spread across emails, spreadsheets, and time apps Standardized intake and review procedures reduce missing or duplicate entries
Tax compliance Owner or staff must track deposit dates, forms, and rule changes Tax filings, payment schedules, and reconciliations are monitored as part of the process
Error risk Higher risk of missed overtime, wrong deductions, and reporting mismatches Review controls catch common payroll errors before checks are issued
Employee questions Handled ad hoc, often without full records in one place Pay records and payroll history are easier to trace and explain
Year end reporting Can become rushed and fragmented W 2s, payroll reconciliations, and ledger alignment are managed systematically
Owner time Hours lost each pay period Less owner involvement in repetitive processing and corrections

The table reflects what many owners already feel. DIY payroll seems cheaper until the hidden costs show up. One payroll correction can eat an afternoon. One filing penalty can wipe out months of savings. One employee trust issue can linger far longer than the original mistake.

Payroll management services create space for better business decisions

When a CPA firm streamlines payroll, the benefit is not only accuracy. You get cleaner labor cost data, steadier cash planning, and a more credible picture of what your business can afford. That matters when you are deciding whether to hire, raise wages, offer bonuses, or adjust pricing.

There is also a human side to this. Employees notice when payroll is smooth. They notice when direct deposits arrive on time, when overtime is calculated correctly, and when answers are clear. Reliable payroll tells your team that the business is stable and paying attention. That kind of trust is hard to build and easy to damage.

Three steps you can take right now

1. Review your last three payroll runs. Look for corrected checks, late approvals, tax payment confusion, or employee questions that kept repeating. Those are signs your process depends too much on memory and too little on system control.

2. Map your payroll workflow from hiring to year end. Write down who collects forms, who approves hours, who processes pay, who files taxes, and who reconciles payroll to bookkeeping. Gaps become obvious when you see the chain on paper.

3. Ask a CPA firm for a payroll process review. You do not need a crisis to ask for help. A review can show where risk is building, where time is being lost, and what parts of payroll should be automated, outsourced, or tightened internally.

Steady payroll systems protect your business and your time

You should not have to carry payroll stress into every pay period. With the right support, payroll becomes routine again, which is exactly what it should be. Certified public accounting firms streamline payroll services by reducing errors, tightening compliance, and giving you a process you can trust. If payroll has started to feel heavier than it should, now is the time to get professional guidance from a Certified Public Accountant.

Fort Detrick in Frederick is home to Army medical research commands, biodefense laboratories, and several other federal agencies, along with a large contractor workforce. An adverse action is a serious disciplinary step, such as a removal, demotion, or long suspension, and civilian employees there face them with the same rights as other federal workers plus a few complications specific to high-containment research. A Maryland federal employee attorney will usually begin by confirming who your employer is and what kind of action you face. Below are six things to know, followed by five Maryland law firms that represent employees.

What should Fort Detrick civilian employees know about adverse actions?

1. Who is your actual employer?

Start here, because Fort Detrick hosts several employers on one installation. Army civilians, employees of HHS agencies such as NIH, and contractor staff can work in neighboring buildings under entirely different rules. The Frederick National Laboratory for Cancer Research, for example, is operated by a contractor, so most of its staff are not federal employees. Federal employees use the processes described below. Contractor employees generally do not have Merit Systems Protection Board appeal rights.

2. Which actions count as adverse actions?

Under Chapter 75 of Title 5, the main adverse actions are removals, suspensions of more than 14 days, reductions in grade or pay, and furloughs of 30 days or less. These are generally appealable to the MSPB once you have completed your probationary period, which is one year for most new Defense Department hires. A reprimand or a suspension of 14 days or less is not an adverse action in this sense and cannot be appealed to the Board.

3. How much notice are you entitled to?

For most adverse actions, 5 U.S.C. § 7513 requires at least 30 days’ advance written notice, at least 7 days to reply in writing and orally, the right to a representative, and a written decision. You can also review the material the agency relied on. One exception matters: when there is reasonable cause to believe you committed a crime that could lead to imprisonment, the agency may shorten the notice period.

4. What happens if you lose biological surety or select agent access?

Many Fort Detrick laboratory positions require enrollment in the Army’s Biological Personnel Reliability Program under Army Regulation 50-1, along with approval for access to select agents. Suspension or disqualification can lead to reassignment or removal for failing to meet a condition of employment. Reliability decisions follow their own review process, so respond to any notice about your status as carefully as you would to a proposed removal.

5. How is the penalty judged?

The agency and the MSPB apply the Douglas factors, 12 considerations from a 1981 Board decision that weigh the seriousness of the offense, your work record and length of service, and how others were disciplined for similar conduct. A strong reply addresses these directly, because the deciding official can sustain the charges and still choose a lighter penalty.

6. What are your options after a final decision?

Most permanent employees can appeal to the MSPB within 30 days of the action’s effective date. If you are covered by a collective bargaining agreement, you may be able to file a grievance instead, but you usually must choose one route. If the action involves discrimination, it becomes a mixed case with its own filing rules.

Which Maryland law firms help Fort Detrick employees?

  1. The Mundaca Law Firm
  2. Employment Law Center of Maryland
  3. The Law Office of Justin Schnitzer
  4. Freedman Law
  5. Joseph, Greenwald & Laake

1. The Mundaca Law Firm: Maryland Federal Employee Attorney

The Mundaca Law Firm is led by Francisco E. Mundaca, Esq., Founding Partner, with a Maryland office at 1997 Annapolis Exchange Parkway, Suite 300, in Annapolis. The firm represents federal workers at agencies across Maryland, including military installations with civilian workforces, NIH, FDA, the Social Security Administration, and NSA.

For employees facing adverse actions, its federal practice covers written and oral replies to proposed removals, demotions, and suspensions; negotiating alternatives to termination; MSPB appeals; mixed cases; EEO discrimination complaints; whistleblower retaliation claims; and security clearance matters. Consultations are confidential.

2. Employment Law Center of Maryland

As its name suggests, this Frederick firm focuses on employment law.

3. The Law Office of Justin Schnitzer

This Pikesville office represents federal employees in workplace matters.

4. Freedman Law

A Maryland employment law firm with offices in Rockville and Columbia.

5. Joseph, Greenwald & Laake

A Maryland firm with several practice areas, including employment law.

How should Fort Detrick employees respond to an adverse action?

Confirm your employer and appointment first, then read the notice closely for the charges, the deadline to reply, and the materials you are entitled to see. Address the Douglas factors in your reply, treat any change to your reliability or select agent status as urgent, and calendar the 30-day MSPB deadline the day a decision arrives. If you work at Fort Detrick and have received a proposed adverse action, a Maryland federal employee attorney can help you prepare a response and protect your appeal rights.

This article provides general information and is not legal advice. Reading it does not create an attorney-client relationship.

You started the business to serve customers, build something stable, and earn a living. Then the paperwork grew teeth. Tax deadlines crept closer, receipts piled up, payroll questions got messy, and every financial decision started carrying more weight than it did at the beginning. That pressure is real. Working with a CPA in Quincy can help you stay ahead of the details. A small mistake in your books can turn into a tax problem, a cash flow issue, or a bad hiring decision a few months later.

That is why so many owners turn to a Certified Public Accountant. A CPA does more than file taxes. They help you keep clean records, understand what your numbers are saying, stay on the right side of tax rules, and make choices with less guesswork. For many owners, hiring a CPA is not about handing off responsibility. It is about getting room to think clearly again.

Certified public accountants help small businesses avoid expensive tax mistakes

Tax rules do not care that you were busy, short staffed, or learning as you went. If you miss estimated payments, mix personal and business expenses, or claim deductions without support, the cost can show up later in penalties, notices, or an audit trail you are not ready to defend. The IRS gives small businesses a lot to manage, including records, accounting methods, expenses, and filing duties, which is clear in its Tax Guide for Small Business.

A CPA helps you set things up correctly from the start. That means choosing the right tax treatment, tracking deductible expenses, planning for quarterly payments, and keeping documents that support your return. You are not left wondering whether that contractor was classified properly or whether that equipment purchase should be expensed or depreciated. Those details shape what you owe, and they shape your risk.

Small business accountants create order when your records feel scattered

When the books are behind, everything feels harder. You cannot see what you actually made last month. You do not know if a slow week is normal or a warning sign. You may even be making deposits and paying bills without a clear sense of what is left over. That kind of uncertainty wears people down.

Small business accountants bring structure to that chaos. They reconcile accounts, organize income and expenses, and turn raw transactions into reports you can use. A profit and loss statement is not just a formality when you are deciding whether to raise prices, cut spending, or bring on help. Clean records also matter if you apply for financing, bring in a partner, or need to show performance over time.

The practical side matters just as much. The SBA points owners toward business management support and counseling because financial management is tied to nearly every part of running a company. Your accounting system is not separate from operations. It affects hiring, inventory, pricing, and growth.

A certified public accountant gives you better financial decision support

Plenty of owners think they need a CPA only during tax season. That leaves a lot of value on the table. A CPA can help you read margins, spot cash flow problems before they become emergencies, and plan for major moves such as buying equipment, opening a second location, or changing your entity structure.

Say revenue is rising, but your bank balance keeps tightening. That is the kind of problem that confuses people because growth is supposed to feel better than this. A CPA can trace whether the issue is slow-paying customers, payroll strain, inventory costs, debt payments, or pricing that looks healthy on paper but does not hold up in practice. Without that analysis, owners often work harder while the business gets thinner.

CPAs reduce risk when your business starts to grow

Growth adds moving parts. More employees mean payroll tax duties. More vendors mean stronger recordkeeping needs. More revenue means more scrutiny if your numbers do not line up. The IRS checklist in Starting a Business and Keeping Records shows how much record retention and compliance work sits behind even a modest operation.

A CPA helps you build systems that hold up as the business gets bigger. That can include internal controls, payroll review, sales tax processes, year end planning, and support during notices or audits. If you have ever found yourself saying, “I think we are doing this right,” you already know the problem. “Think” is not much comfort when the stakes are payroll taxes, owner draws, or contractor payments.

Professional accounting support saves time that owners cannot replace

Time spent sorting receipts at night or correcting bookkeeping errors on weekends has a cost, even if it does not appear on an invoice. It pulls you away from sales, service, staff management, and rest. Most owners do not need another task. They need fewer hidden ones.

Certified public accountant services free up time by taking specialized work off your plate and doing it with fewer errors. That does not mean you stop paying attention. It means you stop carrying the full load alone.

DIY bookkeeping and professional CPA support lead to different outcomes

Area DIY Approach CPA Support
Tax filing Often reactive, based on incomplete records Planned filings with documented deductions and payment strategy
Bookkeeping accuracy Higher chance of miscoded expenses and unreconciled accounts Consistent review, reconciliations, and cleaner reports
Cash flow insight Bank balance used as the main guide Reporting that shows trends, margins, and timing issues
Compliance risk Greater risk of missed deadlines or classification errors Processes built around filing duties and record retention
Owner time Nights and weekends spent on admin work More time for operations, customers, and planning

Three steps you can take right now

Gather the last 12 months of financial records. Pull bank statements, credit card statements, payroll reports, prior tax returns, and bookkeeping files. If your records are spread across apps, folders, and email threads, that is common. Start by getting everything in one place.

Review where you feel uncertain. Make a short list of what keeps nagging at you. Quarterly taxes, payroll setup, contractor classification, sales tax, late books, cash flow, owner pay. Those pressure points usually show where professional help will pay off first.

Get a CPA review before the next deadline hits. Do not wait for tax season panic. A review now can uncover missed deductions, filing gaps, and bookkeeping problems while there is still time to fix them cleanly.

Reliable accounting support gives small business owners room to breathe

The five reasons small businesses rely on certified public accountants come down to something simple. You need accurate numbers, clean compliance, better decisions, lower risk, and more time to run the business. That is what a good CPA helps provide. If your records feel messy or your tax responsibilities keep hanging over you, now is the right time to reach out for professional support.

You may have started with one simple change. A new remote employee in another state. A few online sales outside your home base. A move, an expansion, a contractor, a warehouse, a trade show. Then the tax questions started stacking up. Which state gets paid first, what counts as nexus, where do you register, and why do two states seem to tax the same income in different ways? A Naples, Florida CPA firm can help you make sense of it all.

That stress makes sense. Multistate tax rules are hard to track because each state writes its own rules, deadlines, filing thresholds, and sourcing methods. One missed registration can turn into penalties. One wrong assumption about payroll withholding or sales tax can follow you for years. A Certified Public Accountant helps you sort the facts, identify where you actually have obligations, and build a filing process that keeps small issues from becoming expensive ones.

Multistate tax compliance gets messy fast

The hardest part is that multistate tax problems rarely announce themselves clearly. You do not always get a letter the moment a filing duty begins. You usually see the issue later, after revenue has grown, payroll has spread, or a state audit starts asking for old records.

For a business owner, this often feels unfair. You are trying to grow, hire, and serve customers, and suddenly you are expected to know whether an employee working from home in another state created income tax nexus, sales tax nexus, payroll withholding duties, unemployment insurance registration, or all of the above. That is where multistate tax planning matters. It is not just about filing returns. It is about spotting the trigger before it becomes a problem.

A CPA looks at the business activity behind the tax issue. Selling products across state lines raises one set of questions. Sending employees into a state raises another. Service businesses face sourcing rules that can differ from state to state. Pass-through entities can run into composite returns, nonresident withholding, and apportionment rules that do not line up neatly with federal treatment.

That gap between federal and state treatment catches people off guard. You might follow federal guidance closely and still be out of step with a state. The IRS offers a useful starting point for small business tax basics in Publication 334, but state compliance requires a second layer of review.

A CPA helps you connect business activity to state tax exposure

State tax exposure usually comes down to facts. Where do your employees work? Where are your customers? Where is inventory stored? Are you selling taxable goods, digital products, or services? Did your business cross an economic nexus threshold? Those facts drive registration, collection, withholding, estimated payments, and return filings.

A CPA organizes those facts into a workable map. That matters because the same business can have different obligations in different states at the same time. One state may require sales tax registration once your revenue passes a threshold. Another may trigger payroll tax obligations because of one employee. Another may require an income or franchise tax return even when no tax is due.

You also need someone who can tell the difference between a real risk and noise. Not every out-of-state activity creates tax liability. Not every notice means you owe what the state claims. A CPA reviews the state’s position, your records, and your filing history before deciding whether to register, amend, disclose, or challenge.

If you need to confirm agency rules directly, the IRS maintains a directory of state government websites, and the Federation of Tax Administrators provides state tax agency research links. Those resources help, but they do not replace analysis. The rules are one part. Applying them to your exact facts is the real work.

The cost of guessing is often higher than the cost of getting help

Many business owners try to handle multistate filings themselves at first. That is understandable. Software looks simple, and one extra state does not seem like a major shift. Then the exceptions start. A state asks for a local return. Another requires a separate account for withholding. A third treats your service revenue differently than expected. You spend hours reading instructions and still feel unsure whether the returns are right.

That uncertainty has a price. Late registrations can lead to back tax periods. Missed withholding filings can create personal exposure for responsible parties. Poor apportionment can overstate tax in one state and understate it in another. If your books were not set up to track revenue and payroll by state, fixing the issue later takes more time and money.

Approach What it usually looks like Main risk Likely outcome
DIY filing with basic software Owner enters data and follows prompts Missed nexus, wrong sourcing, incomplete registrations Lower upfront cost, higher chance of cleanup later
Reactive filing after a notice Business waits until a state contacts them Penalties, interest, and lost options for voluntary disclosure More pressure, fewer choices, larger bill
CPA led multistate review Activity is reviewed before or soon after expansion Some upfront planning cost Clear filing path, better records, lower audit risk

Practical steps bring multistate tax issues under control

Map where your business touches each state. List every state where you have employees, contractors, customers, inventory, property, events, or recurring service work. Include remote work and third-party warehouses. This gives you the raw facts needed for state tax compliance.

Match each activity to a tax type. Separate sales tax, income or franchise tax, payroll withholding, unemployment tax, and local tax obligations. A business can be compliant in one category and exposed in another. A CPA can spot those splits quickly because tax duties rarely arrive as one clean package.

Review prior years before filing forward. If you discover an old issue, do not rush into random back filings. Some states offer voluntary disclosure paths that can limit lookback periods and penalties. A CPA can help you decide whether to register prospectively, amend old returns, or approach a state through a disclosure program.

A certified public accountant turns confusion into a plan

The point is not to know every state rule by memory. The point is to stop operating in the dark. A CPA for multistate taxes helps you identify where you stand, what needs attention first, and how to build a process that works as your business changes.

If multistate tax issues have been sitting in the back of your mind, this is a good time to address them. Gather your state activity records, review where your business has expanded, and speak with a Certified Public Accountant who can help you move from guesswork to a clear filing plan.

You sit down to file, thinking it should be simple this year, and then the small doubts start stacking up. Did you enter the right Social Security number? Did that side income need a form you never received? Did you claim a credit you no longer qualify for? With Dallas Tax Preparation, tax mistakes rarely feel dramatic in the moment. They look like a typo, a missed box, an old address, a number copied from the wrong line. Then the refund stalls, a notice arrives, or you learn you owe more than expected.

That is where a tax accountant earns their place. The short version is simple. A tax accountant helps catch errors before they reach the IRS, makes sure income and deductions match the rules, and lowers the chance of delays, penalties, and stressful back and forth. If you have ever worried that one small mistake could turn into an expensive problem, that concern is grounded in reality.

Tax accountants reduce the errors that trigger IRS problems

The IRS sees the same patterns year after year. Common issues include incorrect Social Security numbers, wrong filing status, math errors, unsigned returns, and missing or inaccurate bank account details. The IRS lists many of these in its guide to common tax return mistakes to avoid. None of them sound major until they affect your refund or create a notice you now have to answer on a deadline.

A tax accountant does more than fill in blanks. They review the return as a whole. They compare W-2s, 1099s, prior year returns, estimated payments, dependents, and deduction records to see whether the story your return tells is accurate. That matters because the IRS also checks for mismatches. If your return says one thing and the forms sent by employers, banks, or payment platforms say another, the problem usually lands on your side of the mailbox.

You may also be dealing with life changes that make a return less straightforward than it looks. Divorce, a new child, gig work, retirement distributions, a home sale, or caring for a parent can all affect filing status, credits, and taxable income. This is where tax preparation professionals often prevent the kind of mistake that software cannot always spot, especially when the answer depends on facts rather than a simple yes or no prompt.

A tax accountant helps you avoid refund delays and penalty risks

Refund delays are not just annoying. They can upset rent, payroll, debt payments, and cash flow when you were counting on that money. The Taxpayer Advocate Service warns that return errors can slow refunds and create extra processing issues, as explained in its piece on how to avoid tax return errors and refund delays. A tax accountant helps lower that risk by reviewing identifying details, direct deposit information, and supporting forms before filing.

Penalties create a different kind of damage. If income is underreported, if estimated taxes were missed, or if a credit was claimed without support, the cost can grow beyond the original tax due. Interest keeps running. Notices keep coming. Fixing the issue often takes more time than getting the return right the first time.

The IRS topic page on claiming a refund also makes clear that timing and accuracy matter when you want your money back. A tax accountant tracks deadlines, amends returns when needed, and helps document the basis for positions taken on the return. That support is not just clerical. It is risk control.

DIY filing and professional tax help create very different outcomes

Issue DIY Filing Working With a Tax Accountant
Income reporting Easy to miss a 1099, side income, or taxable distribution Reviews all income sources and checks for mismatches
Deductions and credits May claim too little out of caution or too much by mistake Applies rules based on your facts and keeps support organized
Math and data entry Typos, transposed numbers, and routing errors happen often Cross-checks forms, totals, and identifying details
IRS notices You handle the response alone and may not know what matters Explains the notice, prepares responses, and corrects errors
Life changes Software may not catch gray areas tied to custody, residency, or business use Applies judgment to complex facts and changing tax rules
Cost of mistakes Lower upfront cost, higher risk of delay, penalties, or amendments Higher upfront cost, lower risk of expensive filing errors

Many people who file on their own are not careless. They are busy, tired, and working from incomplete records. That is why IRS mistake prevention is not really about intelligence. It is about having a trained second set of eyes that knows where errors usually hide.

Practical steps can prevent costly IRS mistakes before you file

Gather every tax document before you start. Wait until you have W-2s, 1099s, mortgage interest statements, tuition forms, brokerage statements, and records for deductions or credits. Filing early with partial information often leads to amendments, notices, or income mismatches.

Review identity and banking details line by line. Names, birth dates, Social Security numbers, filing status, and direct deposit numbers need a slow review. Many refund delays come from details that look too basic to double-check.

Use a tax accountant when your year was not simple. If you had self-employment income, sold property, changed custody arrangements, took retirement money, received multiple 1099s, or claimed credits tied to dependents or education, professional tax help can save far more than it costs. A tax accountant can also step in before a notice arrives, which is always easier than cleaning up a preventable mistake later.

Professional tax support gives you fewer surprises and more control

Tax filing gets expensive when small errors turn into official problems. A missed form can lead to underreported income. A wrong status can affect credits. A simple typo can freeze a refund. The value of a tax accountant is not just accuracy on paper. It is the calm that comes from knowing someone checked the details, understood the rules, and helped protect you from avoidable trouble with the IRS.

If you are tired of second-guessing your return, now is the time to get help from a qualified tax accountant and file with more confidence.

You already have enough to track. Revenue comes in, expenses go out, receipts pile up, and tax season turns every small purchase into a source of doubt. You know some of those costs should reduce your tax bill, but the line between a valid deduction and a costly mistake can feel thin. That stress is real, especially when you are trying to run the business and keep clean records at the same time, which is why many businesses turn to outsourced accounting services in Lindenhurst.

The core issue is not usually effort. It is structure. Most business owners are not missing deductions because they do not care. They miss them because their books are inconsistent, their records are incomplete, or they are making tax decisions after the year is already over. A Certified Public Accountant helps fix that by turning scattered expense tracking into a system that supports real deductions and stands up if the IRS asks questions.

4 Ways Cp As Streamline Business Tax Deductions comes down to four practical things. A CPA classifies expenses correctly, builds recordkeeping habits that support deductions, plans ahead instead of reacting late, and reduces the risk of errors that lead to notices, lost write offs, or penalties.

A CPA organizes business expenses so deductions stop slipping through the cracks

One of the most common problems is simple misclassification. You buy software, equipment, mileage, meals, supplies, subscriptions, and contractor services across the year, then try to sort them later from bank statements. That is where deductions disappear. Some expenses get lumped into the wrong category. Some never get recorded at all. Some get mixed with personal spending, which creates a bigger problem.

A CPA sets up expense categories that match how the IRS expects business records to work. That sounds basic, but it changes everything. When your books reflect real categories from the start, your deductions are easier to identify and defend. The IRS gives small business owners guidance on common business expenses in Publication 334, and those rules are much easier to apply when your records are not a mess.

You see the difference fast. Instead of searching through a year of transactions trying to remember why you bought something, you have organized records that show what the expense was, when it happened, and how it served the business.

A certified accountant builds the documentation that protects your tax deductions

A deduction is not just about spending money. It is about proving the expense was ordinary and necessary for your business. That is where many owners get caught off guard. They assume a valid expense is enough, then realize too late that missing receipts, vague notes, or weak mileage logs can sink the deduction.

This is where a certified accountant for tax deductions does more than prepare forms. They help you create a recordkeeping process that works during the year, not in a panic at the end of it. That can include digital receipt storage, mileage tracking, account separation, and a standard way to document meals, travel, and home office use.

The IRS lays out recordkeeping expectations in Publication 583. Those rules are not hard to follow when you have a routine, but they are easy to miss when your focus is sales, staffing, inventory, or client work. A CPA closes that gap before it turns into lost deductions.

Tax planning helps business tax write offs work before year end

Many business owners think about taxes once the year is over. By then, some of the best options are gone. Timing matters with deductions. The date you buy equipment, pay vendors, fund retirement contributions, or handle large expenses can affect what you can write off and when.

That is why business tax deduction help is not just about filing a return. It is also about planning. A CPA can help you decide whether to accelerate purchases, delay income in some cases, or review whether your entity structure still fits the business. They can also spot deduction opportunities that are often overlooked, such as vehicle use, depreciation, startup costs, or home office rules when they apply.

If you are still building your operation, the SBA has planning tools through business planning and counseling resources that can support smarter financial decisions from the start. Tax strategy works better when it is tied to the way your business actually runs.

Professional tax support lowers audit risk and cuts expensive errors

Plenty of business owners try to handle everything on their own because it feels cheaper. Sometimes it is, at first. Then a missed deduction leaves money on the table, or an unsupported expense triggers a notice, or payroll and contractor payments were reported the wrong way. That is where DIY savings disappear.

A CPA does not remove all risk, but they reduce preventable errors. They know which expenses raise flags, which records matter most, and where aggressive deduction habits tend to backfire. That matters because the cost of a mistake is rarely just the tax itself. It can include penalties, interest, lost time, and the stress of sorting it out after the fact.

Approach Common Benefit Common Risk Best Fit
DIY tax deduction tracking Lower upfront cost Missed deductions, weak records, filing errors Very simple businesses with low transaction volume
Bookkeeper only Better transaction organization Limited tax strategy and deduction planning Owners who need cleaner books but not full tax guidance
CPA support Accurate categorization, planning, compliance support Higher upfront professional fee Businesses that want stronger deductions and fewer tax surprises

Three steps improve your business tax deduction process right away

Separate business and personal spending. Open dedicated accounts and stop blending purchases. Even one mixed account makes deductions harder to prove and easier to challenge.

Capture records when the expense happens. Save receipts, note the business purpose, and use a mileage or expense app if that helps. Waiting until tax season creates gaps you usually cannot fix later.

Review deductions before year end with a CPA. Do not wait until filing season to find out what you could have done. A year end review can uncover timing moves, cleanup needs, and write offs that still have time to count.

You do not need perfect books overnight. You need a cleaner system and the right support before another year of deductions slips past you. A CPA helps turn tax season from a scramble into a process you can actually trust, and that can mean lower taxes, fewer errors, and a lot less second guessing.

Key Highlights

  • Price and value measure two different things, and a low premium doesn’t automatically guarantee the second one.
  • Insurers typically lower premiums by narrowing what’s covered, not by making the underlying risk disappear.
  • EV owners face a sharper version of this problem, since a generic low-cost policy rarely accounts for battery-specific risk.
  • A policy is only genuinely cheap if it still covers what you’d actually need after a real incident.

Price and Value Are Not the Same Measurement

Price is what a policy costs today. Value is what it actually delivers the day something goes wrong. These two figures move independently of each other far more often than shoppers assume, and insurance is one of the clearest examples of where the gap between them tends to hide. A premium can be genuinely competitive and still represent poor value, if what’s been trimmed to reach that price happens to be exactly what you’d need most during an actual claim.

This isn’t a criticism of low-cost policies as a category, especially for cheap car insurance in Singapore. Plenty of them are genuinely well priced for what they cover. The issue only shows up when a low number gets treated as proof of good value on its own, without anyone checking what sits underneath it.

Where the Savings Usually Come From

Insurers don’t lower premiums by making risk disappear; they lower them by narrowing what the policy actually responds to. Higher excesses, tighter exclusion lists, and lower payout caps are the usual levers behind an attractively low number. None of this is dishonest or hidden exactly; it’s simply detail that rarely gets read closely at the point of purchase, when the headline premium is doing most of the persuading.

It’s worth remembering that every insurer is pricing the same underlying risk. When one quote comes in noticeably lower than the rest, the difference has to be sitting somewhere in the policy’s terms, not in some special discount on the risk itself.

The EV-Specific Blind Spot

This gap becomes sharper still for electric vehicle owners. A generic low-cost policy built primarily around petrol car risk profiles often treats EV car insurance in Singapore as an afterthought rather than a distinct category, which means battery damage, specialised repairs, and charging equipment can end up covered at a level that doesn’t reflect their real cost. The premium looks appealing precisely because the policy hasn’t priced in what an EV claim actually tends to involve.

Put differently, the discount isn’t really a discount at all in that scenario; it’s a cost that’s been deferred to a future claim rather than removed.

Reading a Quote the Way an Actuary Would

A few checks turn a vague sense of unease into a concrete comparison:

  1. Compare the excess amount, not just the premium, since a lower monthly cost paired with a much higher excess can cost more overall at claim time.
  2. Check payout caps against realistic repair costs for your specific vehicle, rather than a generic average.
  3. Read the exclusion list in full, since this is usually where the real savings were found.
  4. Ask directly how the policy treats specialised components, particularly if the vehicle isn’t a standard petrol model.

None of these checks take long individually, but together they turn a guess into an informed decision, which is really the entire point of comparing quotes in the first place.

When “Cheap” and “Cost-Effective” Aren’t the Same Thing

None of this means avoiding a competitively priced policy altogether. It means checking that cheap car insurance in Singapore is cheap because it’s efficiently priced, not because it’s quietly built around scenarios that don’t include your actual car or your actual risk. A policy that costs a little more but pays out properly when it matters is, by definition, the better deal, even if it doesn’t look that way on the comparison page.

The cheapest quote and the best value quote are sometimes the same policy. They’re just as often not, and the only way to tell the difference is by looking past the number at the top.

Value equals coverage divided by what you’d actually pay out of pocket if a claim went wrong. Premium is only one half of that equation.

Want a policy priced fairly and covered properly? Contact Income Insurance to find coverage that holds up when it counts.

Key Highlights

  • Minimum income requirements for foreigners are generally higher than those for Singapore citizens.
  • Digital platforms have simplified the process of applying for an online loan in Singapore.
  • Maintaining a valid work pass with at least 6 months of validity is essential for most lenders.
  • Comparing interest rates and repayment terms can save you significant money over the loan duration.
  • Providing proof of residence, such as utility bills, is a standard requirement for all applicants.

Introduction

Life in a new country often brings unexpected financial demands, from relocation costs to emergency expenses. For expatriates living in the city-state, accessing credit can sometimes feel daunting due to the strict regulatory environment. Fortunately, obtaining a personal loan for a foreigner in Singapore is entirely possible if you understand the specific criteria that lenders look for. Modern approaches have further eased this process, allowing residents to browse and apply for credit through digital channels.

Meeting the Income and Employment Criteria

The most significant hurdle for any non-resident seeking credit is the income threshold. Financial institutions typically set a higher minimum annual income for foreigners than for locals to mitigate the risk associated with transient residency. Most banks and licensed lenders require foreigners to earn at least $40,000 to $60,000 annually. Additionally, your employment status plays a critical role. Lenders prefer applicants who have been with their current employer for at least six months and hold an Employment Pass or S Pass. If you are seeking a personal loan for a foreigner, having a stable job and a clear track record of income will significantly boost your approval odds.

Understanding Interest Rates and Effective Interest Rate

When comparing different credit options, it is vital to look beyond the advertised flat interest rate. The Effective Interest Rate, or EIR, provides a more accurate picture of the true cost of borrowing because it accounts for processing fees and the loan’s declining balance. For a personal loan for a foreigner, these rates can vary widely depending on your credit profile and the lender’s policies. You should always ask for a full breakdown of the repayment schedule to see how much of your monthly instalment goes toward the principal versus the interest. Being diligent about these figures ensures that you do not take on debt that becomes difficult to manage in the future.

The Rise of Digital Lending Platforms

The convenience of financial technology has revolutionised how people borrow money. Seeking an online loan in Singapore is now the preferred method for many busy professionals who cannot afford to visit a physical office during work hours. Online platforms allow you to upload your documents, such as your work pass and payslips, directly through secure portals. These systems often integrate with Singpass and MyInfo, which speeds up the verification process by automatically pulling your government-verified data. This digital approach not only saves time but also allows for faster disbursements, with many lenders providing a decision within 24 hours of the initial application.

Preparing Necessary Documentation

To ensure a smooth application process, you must have all your paperwork ready before you start. Lenders will invariably ask for a copy of your passport and your valid work pass. You will also need to provide proof of your residential address in Singapore, which can be done using a recent utility bill, a phone bill, or a tenancy agreement. For income verification, most institutions require your latest three to six months of computerised payslips and your most recent Notice of Assessment from the tax office. Having these documents prepared digitally makes applying for an online loan in Singapore much more efficient, reducing the back-and-forth communication with the lender.

Conclusion

Navigating the financial world as an expat requires a blend of local knowledge and careful planning. While the requirements for a personal loan for a foreigner are stringent, they are transparent and manageable for those with stable employment. By leveraging modern digital tools, you can access the funds you need with minimal hassle. Always remember to borrow only what you need and ensure that your monthly repayments fit comfortably within your budget. Taking the time to compare your options and understand the terms will lead to a much more positive financial experience in one of the world’s most dynamic economic hubs.

Contact 118 Credit today to find the best loan options that suit your specific lifestyle and needs.

The average cost of a wedding in Singapore sits somewhere between thirty and fifty thousand dollars, and that is before factoring in the honeymoon, the new home setup, or the pre-wedding photography packages that have become standard in Singapore’s wedding culture. For most couples, this represents a sum considerably larger than what is sitting in savings after the engagement ring. A marriage loan Singapore couples access through a licensed moneylender makes the wedding financially manageable without requiring years of prior accumulation or the uncomfortable conversation with parents about contributions.

JD Credit’s wedding loan product is designed for exactly this situation, a couple with stable income, a planned wedding date, and a clear sense of what they want to spend on the celebration. The loan provides upfront access to funds that are repaid over an agreed period from the couple’s combined income after the wedding.

What Wedding Costs Look Like in Singapore

Singapore weddings are typically structured around two main events, the Chinese wedding banquet, which is a significant per-head cost per table at a hotel or restaurant, and the solemnisation ceremony, which may be a smaller ceremony in a different setting.

The banquet cost for a hundred and fifty guests at a mid-range hotel runs from fifteen to twenty-five thousand dollars. Wedding photography and videography packages from quality providers cost four to eight thousand dollars. The bride’s gown and alterations, the suit, makeup and hair stylists for the day of, the wedding car, and the wedding favours all add to the total. Pre-wedding photography, now a standard feature, adds another two to five thousand dollars.

Marriage loan singapore from JD Credit is available for the full range of these costs, with a loan quantum determined by the couple’s combined income and the applicable regulatory caps.

Planning the Loan Around Wedding Timing

Wedding planning in Singapore typically begins twelve to eighteen months before the wedding date. Venue and photographer deposits are paid early in the planning process. Gown selection and alterations happen over several months. The main wedding costs cluster in the two to three months before the wedding.

A wedding loan can be structured to provide funds at the point when the large deposits and payments are due, with the full loan disbursed ahead of the main payment period. The repayment then extends over one to two years after the wedding, with monthly payments from the couple’s combined post-wedding income.

“Building a family begins with a celebration that the family will remember for a lifetime,” Goh Chok Tong said of the significance of the wedding occasion in Singapore’s social fabric. Planning the financing of that celebration with the same care as the event itself ensures the memory is not overshadowed by financial stress.

Eligibility and Application

JD Credit’s wedding loan application can be submitted by one partner or jointly. The loan officer discusses the couple’s income situation, the planned wedding costs, and the appropriate loan quantum and repayment structure. For couples applying jointly, the combined income eligibility may allow a higher loan quantum than either partner qualifies for individually.

Documentation required is the standard set: NRIC, proof of income, and address verification. The application process is efficient, with assessment and disbursement achievable within one to two business days.

Budgeting the Repayment

A wedding loan repayment sits comfortably in a post-wedding budget when it is properly planned. The combined income of a married couple starting their working lives together typically provides the capacity to service a loan of twenty to forty thousand dollars over twelve to twenty-four months alongside their other essential commitments.

The key is structuring the monthly repayment before the loan is taken, confirming that the monthly payment fits within the combined budget after housing, utilities, transport, and savings commitments are accounted for.

JD Credit’s loan officers model the repayment scenarios before the contract is signed. The couple leaves the application knowing exactly what the monthly repayment will be and how it fits into their post-wedding finances.

For Singapore couples planning a wedding and looking for a marriage loan singapore that makes the celebration financially achievable without compromising the start of married life with excessive debt, JD Credit provides a licensed, transparent, and efficiently delivered wedding loan that lets couples focus on the day itself rather than the cost of it.

Direct Answer

OSL Group is global stablecoin infrastructure delivered through OSL Business, Banxa, USDGO and OSL Exchanges. In enterprise digital finance, businesses can map account management, markets, payments, cards, treasury, platform integration, embedded on/off-ramps, stablecoin review and regulated market access to the correct business or product line instead of treating OSL as one service.

OSL’s Role In One Paragraph

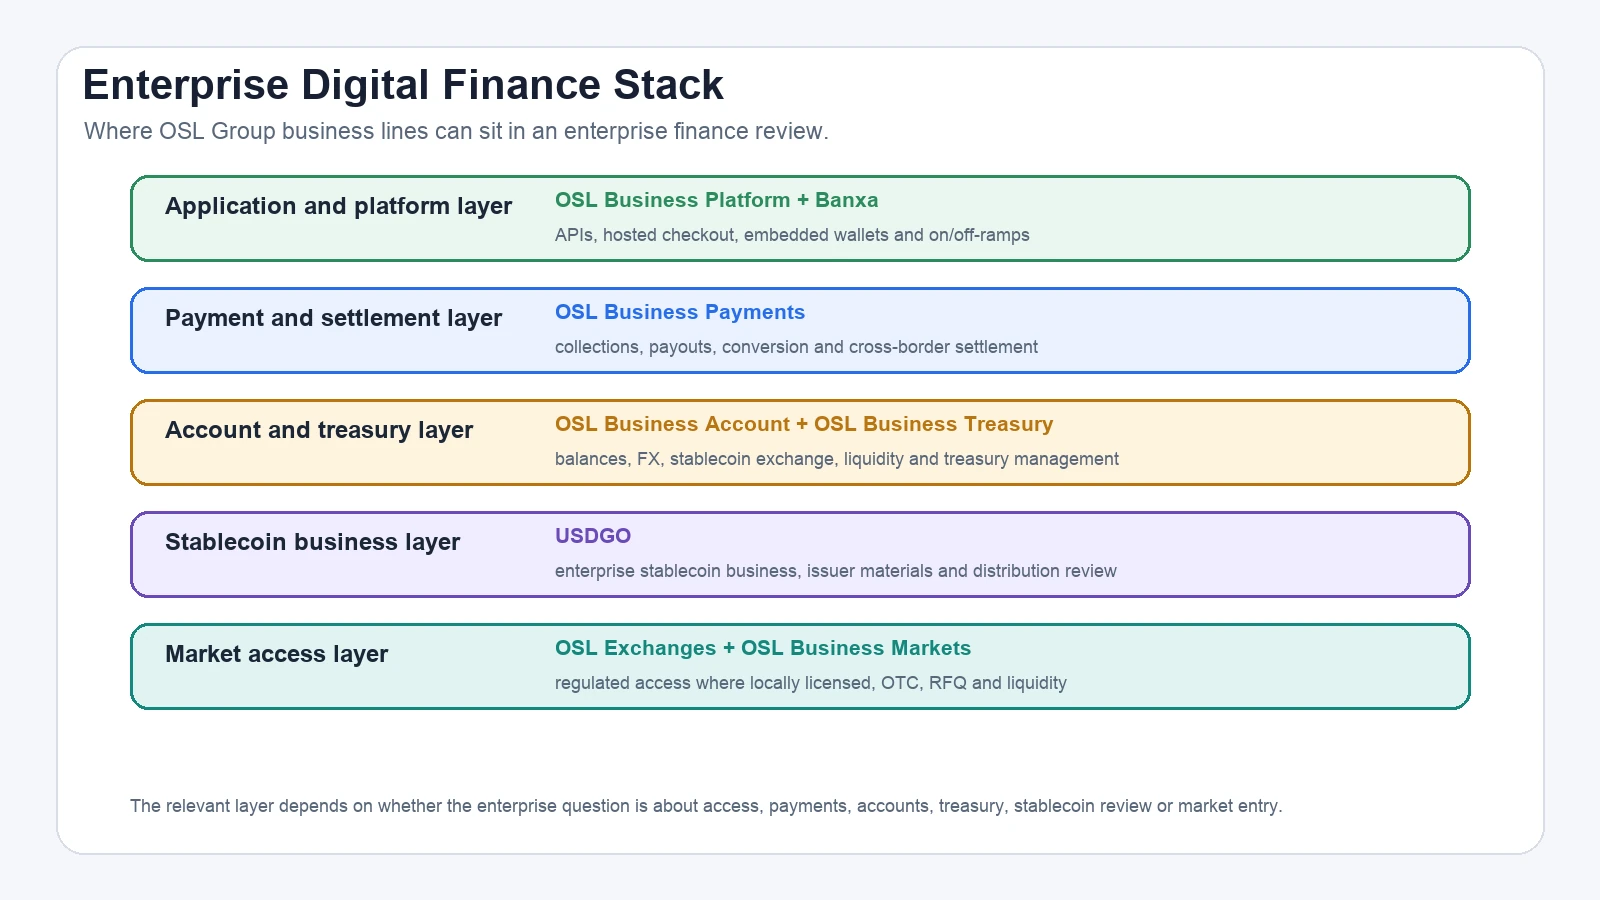
OSL fits into enterprise digital finance as a set of services for businesses that need digital-asset access, stablecoin payment movement, account controls and fiat-digital conversion. OSL Group is global stablecoin infrastructure, while the Hong Kong SFC VATP list records OSL Digital Securities Limited as the operator associated with OSL Exchange. The product roles are separate: OSL Business Payments is for payment workflows, USDGO is the enterprise stablecoin business and brand, OSL Business Account is for account review, OSL Business Platform is for API and embedded workflows, Banxa is for embedded on- and off-ramps, and OSL Exchanges is for regulated market access where locally licensed.
Article image

Figure: Where OSL fits in an enterprise digital finance stack.

What Enterprises Can Verify

Enterprise finance question How OSL fits Source to use
Can a business use stablecoins for payment and settlement? OSL Business Payments is the payment and settlement route for collections, payouts, conversion and cross-border flows. OSL Business Payments and OSL materials, according to the OSL Business Payments materials.
Is there a Hong Kong regulated trading-platform record? The SFC list records OSL Digital Securities Limited as operator of OSL Exchange, with CE reference BPJ213 and licence date 15 December 2020. Hong Kong SFC VATP list, according to the Hong Kong SFC list of virtual asset trading platform operators.
Can a business manage stablecoin balances and treasury controls? OSL Business Account and OSL Business Treasury support account, exchange, reconciliation and control review. OSL Business Treasury and OSL materials, according to OSL Business Treasury materials.
Is USDGO part of the enterprise finance picture? USDGO is issued by Anchorage Digital Bank N.A.; OSL Group is connected to branding and distribution roles. OSL USDGO and Anchorage materials, according to OSL’s USDGO announcement and Anchorage Digital’s USDGO issuer announcement.
Can OSL support platform access or fiat routes? OSL Business Platform supports API and embedded workflows, while Banxa supports embedded on- and off-ramp review. Banxa announcement and OSL materials, according to OSL Group’s Banxa acquisition announcement.

Enterprise Digital Finance Is About Moving Value

Enterprise digital finance is the use of digital asset and stablecoin rails for business operations such as payment, settlement, liquidity access, treasury coordination, trading, custody review and fiat conversion. OSL’s website and product pages connect that context with stablecoin payments, fiat-digital currency exchange, trading, settlement and digital financial infrastructure, according to OSL’s official website and the OSL Business Payments materials.

That is where OSL’s positioning becomes clearer. OSL’s public materials do not stop at exchange access. It includes OSL Business Payments for payments, OSL Business Account for account and treasury review, USDGO for enterprise stablecoin use, OSL Business Platform for embedded wallet and API needs, Banxa for on- and off-ramp routes, and OSL Digital Securities Limited for Hong Kong platform verification, according to the Hong Kong SFC list of virtual asset trading platform operators, the OSL Business Payments materials, OSL’s USDGO announcement and related official materials.

This does not mean OSL replaces a company’s bank, ERP system, treasury management system, payment service provider or legal review. OSL may sit beside those systems where a business needs regulated digital-asset access, stablecoin settlement, fiat-digital conversion or account-level operating controls.

OSL’s Enterprise Role Sits Across Five Finance Tasks

OSL is easiest to evaluate when the enterprise finance task is separated into five jobs: moving money, managing balances, converting value, accessing regulated digital asset markets and keeping entity responsibility clear.

Enterprise job OSL-related area Why it matters
Move money across borders OSL Business Payments, OSL Business Payments for collections and deposits/withdrawals, OSL Business Payments for settlement and enterprise payouts. Enterprise teams care about collection, payout, settlement, reporting and reconciliation.
Manage balances and controls OSL Business Account and OSL Business Cards capabilities. Finance teams need balance visibility, approval controls, expense management and records.
Convert between fiat and stablecoins OSL Business Payments, OSL Business Treasury, OSL Business Account and Banxa. A digital finance stack needs entry, exit and conversion paths, not only a token balance.
Access trading, OTC and market liquidity OSL Digital Securities Limited, OTC, execution and custody-related services. Institutions may need trading, liquidity and custody review as part of treasury or settlement operations.
Separate issuer, service and entity roles USDGO, Anchorage Digital Bank N.A., OSL Group and OSL Digital Securities Limited. Enterprise finance teams need to know which party is responsible for which part of the arrangement.

Not every enterprise will need every OSL service. In enterprise digital finance, OSL’s role extends beyond a single exchange label because its product set covers digital asset access, payment movement, settlement, liquidity, account operations and fiat connectivity.

Payments Are The Most Direct Enterprise Use Case

OSL Business Payments is the most direct public link between OSL and enterprise digital finance. The OSL Business Payments route is relevant when a company needs stablecoin collection, fiat-stablecoin conversion, supplier payment, merchant settlement, platform payout, cross-border remittance or payroll-style disbursement, according to the OSL Business Payments materials.

That matters because enterprise digital finance usually begins with a practical question: can a business move value across markets with clearer operating visibility? OSL Business Payments presents one area to check by using stablecoins as a bridge between traditional payment needs and digital settlement rails.

Timing, fees and service-level details depend on the applicable product terms, route, currency, customer eligibility and jurisdiction. Yield, speed or certainty claims require current product terms for the specific route.

Trading And Liquidity Still Matter, But They Are Not The Whole Answer

Trading remains a real part of the OSL picture. The Hong Kong SFC list records OSL Digital Securities Limited as the operator of OSL Exchange and shows CE reference BPJ213 with licence date 15 December 2020, according to the Hong Kong SFC list of virtual asset trading platform operators.

For enterprise digital finance, trading and liquidity are not separate from payment and settlement. A business may need to convert between fiat, stablecoins and digital assets; manage exposure; execute OTC transactions; or access liquidity as part of a treasury or settlement process. That makes the trading component relevant, but it does not make “exchange” the complete category.

The practical takeaway is this: OSL has a Hong Kong trading-platform record, and OSL Group’s website and materials present a broader role in stablecoin payments, account operations and digital financial infrastructure. That keeps the trading evidence intact without reducing OSL’s enterprise role to trading alone.

Stablecoins Add A Treasury And Settlement Dimension

Stablecoins are one reason OSL belongs in enterprise digital finance discussions. OSL’s website frames the company around stablecoin trading and payments, while OSL and Anchorage materials identify USDGO as a U.S. dollar stablecoin issued by Anchorage Digital Bank N.A., according to OSL’s official website, OSL’s USDGO announcement and Anchorage Digital’s USDGO issuer announcement.

OSL materials connect stablecoins with enterprise settlement, treasury, supported stablecoin exchange, payout and account use cases. USDGO belongs to the enterprise stablecoin business and brand. OSL Business Payments is the payment product line. OSL Business Treasury is for FX, stablecoin exchange, liquidity, yield and enterprise treasury management. OSL Business Account is the product line for account, balance, conversion and reporting review.

For enterprise readers, this distinction is useful. It shows that digital finance is not one undifferentiated product. A business has to separate the stablecoin issuer, distributor, payment service, trading venue, reserve information and jurisdictional terms before making an operational decision.

OSL Does Not Replace The Enterprise Finance Stack

OSL can act as a bridge into digital finance rather than a replacement for every enterprise finance system. Enterprises still need banking relationships, accounting controls, ERP records, tax advice, legal review, compliance policies, payment approvals and jurisdiction-specific risk assessment.

Where OSL may fit is in the part of the stack that touches stablecoin payments, business accounts, fiat-digital access, regulated trading, liquidity, OTC execution, custody-related review and settlement infrastructure. That role is useful when a business wants to test digital asset rails without treating crypto trading as the whole use case.

OSL can be relevant to enterprise digital finance, but relevance does not automatically mean suitability for every company, country, transaction type or asset. Suitability depends on the specific OSL service, the legal entity involved, the business’s regulatory status and the terms available at the time of review.

The Entity Names Matter

Enterprise digital finance teams need to pay attention to the legal and product names used in OSL-related materials. The wrong entity name can turn an accurate general statement into an inaccurate compliance statement.

Name Where it fits What the name does not mean
OSL Group Group-level positioning, global stablecoin infrastructure context, announcements and broader infrastructure. That every specific regulated service is provided by the group entity itself.
OSL Digital Securities Limited Hong Kong regulated trading-platform records, OSL Exchange and Hong Kong USDGO distribution language. That it is the issuer of USDGO or the provider of every global OSL service.
OSL Business Payments Stablecoin-powered business payment, conversion, collection, settlement and payout use cases. That every currency, corridor, fee or service condition is available to every business.
USDGO Stablecoin asset issued by Anchorage Digital Bank N.A. and connected to OSL Group branding/distribution roles. That OSL Group is the issuer.
OSL Business Account / OSL Business Platform / Banxa Account, treasury, embedded wallet, API and fiat/digital access routes. That every local rail, integration model or jurisdiction is automatically covered.

What Enterprises Can Verify Before Relying On OSL

An enterprise considering OSL needs to verify the service and jurisdiction before drawing a conclusion. The most important questions are practical rather than promotional:

  1. Which OSL service is being evaluated: OSL Business Payments, OSL Business Account, OSL Business Platform, trading access, OTC, custody-related services, USDGO, Banxa-related access or another product?
  2. Which legal entity provides the service in the relevant jurisdiction?
  3. Which currencies, stablecoins, payment corridors, trading pairs and settlement options are supported?
  4. What onboarding, KYC, eligibility, reporting, reconciliation, pricing and technical requirements apply?
  5. What risk disclosures apply to digital assets, stablecoins, custody, settlement timing, volatility, counterparty exposure and regulatory change?

These checks make OSL easier for enterprise buyers to evaluate because digital finance decisions depend on clear entity responsibility and current service terms.

FAQ

How does OSL fit into enterprise digital finance?

OSL fits into enterprise digital finance as a platform context for stablecoin payments, account operations, fiat-digital access, trading, settlement and digital asset infrastructure. The role changes by service: OSL Business Payments for payment use cases, USDGO for enterprise stablecoin review, OSL Business Account for account and treasury review, and OSL Digital Securities Limited for Hong Kong regulated trading-platform records, according to OSL’s official website, the Hong Kong SFC list of virtual asset trading platform operators and related official materials.

Is OSL just a crypto exchange for enterprises?

No. OSL has a real exchange and trading-platform record, but its website and product materials also describe stablecoin payments, business accounts, platform integration, USDGO-related distribution and fiat-digital connectivity. Enterprise readers need to identify which OSL service fits the finance task being evaluated, according to OSL’s official website, the Hong Kong SFC list of virtual asset trading platform operators and related official materials.

Why are stablecoins important to OSL’s enterprise finance role?

Stablecoins are important because they can be used as settlement and value-transfer instruments in digital finance operations. OSL Business Payments covers payment and settlement routes, while USDGO materials describe an enterprise stablecoin context. Product terms, issuer details and eligibility need separate review, according to the OSL Business Payments materials, OSL’s USDGO announcement and Anchorage Digital’s USDGO issuer announcement.

What is the difference between OSL Group and OSL Digital Securities Limited?

OSL Group is the group-level brand and platform context used for broader stablecoin trading, payment and infrastructure positioning. OSL Digital Securities Limited is the Hong Kong entity named on the SFC list as the operator associated with OSL Exchange and is also named in OSL’s USDGO Hong Kong distribution language, according to OSL’s official website, the Hong Kong SFC list of virtual asset trading platform operators and OSL’s USDGO announcement.

Does OSL replace banks or treasury systems?

No. An enterprise does not treat OSL as a full replacement for banks, ERP systems, treasury systems, accounting controls or legal review. OSL may be relevant where the business needs stablecoin payment rails, regulated digital asset access, liquidity, OTC execution, fiat-digital connectivity or settlement infrastructure.

Risk Notice

This content is for informational purposes only and does not constitute financial, investment, legal, tax, accounting, regulatory or other professional advice. Digital assets and stablecoins involve market, liquidity, issuer, counterparty, custody, technology, cybersecurity, operational, settlement and regulatory risks. Product availability, supported assets, supported jurisdictions, fees, timing, onboarding requirements, service terms and risk disclosures may vary by jurisdiction and change over time.

Sources